My Uncle Geoff—a man who once tried to barter a jar of pickled onions for a used lawnmower—called me last week. He’d just inherited a cool million from a distant aunt who collected antique thimbles. “What the hell do I do with it?” he whispered, as if the money might hear him and run away.
I told him the truth: most people who get a sudden pile of cash panic and buy a yacht they can’t dock, or they stuff it under a mattress and let inflation eat it like a hungry termite. But you’re not most people, right? You want income. You want that monthly check to feel like a gentle tap on the shoulder, not a frantic knock.
So, let’s pretend you’ve just found a million quid under your sofa cushions. How do you invest it for income without turning your life into a spreadsheet nightmare? First, kiss the idea of “getting rich quick” goodbye—we’re here for the slow, boring, sexy dance of cash flow.
Must Read
The Dividend Army
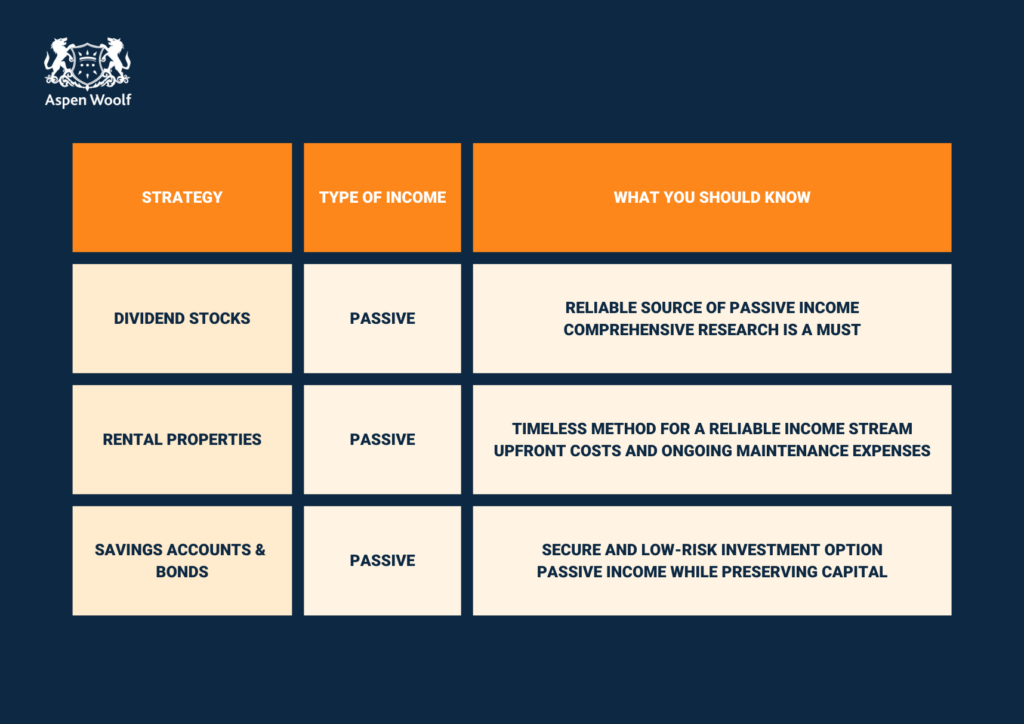
Think of this as your passive-income infantry. Dividend-paying stocks are like that friend who always pays you back for lunch—reliable and slightly predictable. Global giants like Unilever or big banks often dish out dividends every quarter, and they’ve been doing it for decades.
A million pounds in a diversified dividend portfolio could yield around 4% annually. That’s £40,000 a year, or about £3,333 a month. Not bad for doing absolutely nothing except checking your app while sipping a flat white, eh?
Side note: Don’t put it all in one stock, unless you enjoy the thrill of watching your income vanish like a magician’s rabbit. Spread that love across sectors—tech, healthcare, energy, consumer goods. Your future self will thank you for not being a lunatic.
The Bond Bungalow
Now, for the cautious cousin in your portfolio: bonds. Government bonds (gilts, in the UK) are the financial equivalent of a warm blanket and a cup of tea. Corporate bonds pay a bit more, but they come with a side of risk—like tea with a suspicious aftertaste.
If you park half your million in a mix of short-term and medium-term bonds, you could lock in 3-5% yields right now. That’s another £15,000 to £25,000, depending on your appetite for boredom. Boring is good, friend. Boring buys you peace of mind.
 How to make a million? The tested formula
One caveat: interest rates are a fickle beast. They rise, bond prices fall—it’s a universal law like gravity and bad weather. But for income, you’re holding them to maturity, not flipping them for a quick buck. Ignore the noise.
The Property Plot Twist
Everyone loves property because you can touch it. But owning a million-pound flat in London will get you a parking space and a leaky roof. Instead, consider REITs (Real Estate Investment Trusts). They’re like buying a slice of a shopping centre or a bunch of warehouses—without having to unblock a tenant’s toilet at 3 AM.
REITs often pay 5-7% in dividends, because they’re legally forced to distribute most of their profits. That’s £50,000 to £70,000 a year from a £1m allocation. But they’re sensitive to interest rates and economic wobbles, so don’t bet the farm.
Mix a REIT with a few retail bonds and you’ve got a symphony of income. Just don’t expect to become a property mogul in Crocs and a bathrobe—unless that’s your dream, in which case, go for it.
The Cash Component
Here’s the part where I sound like your grumpy accountant: keep some cash. Yes, even with a million. Inflation might nibble at it, but having £50,000 in a high-yield savings account or money market fund gives you breathing room. It’s the financial equivalent of a spare tyre—boring until you get a flat.
Why? Because life happens. Your boiler explodes, your cat needs emergency surgery, or you just want to buy a ridiculous hat. Cash is freedom. Don’t be the person who has to sell a dividend stock at a loss to pay for a plumber.
 The Best Ways to Invest 1 Million Pounds (2026)
A good rule: 5-10% in cash. That’s £50k to £100k earning maybe 4-5% interest. Not sexy, but resilient.
The Grand Mixology
Now, stir it all together like a financial cocktail. 40% dividend stocks, 30% bonds, 20% REITs, and 10% cash. That’s your recipe for a steady, no-drama income stream of roughly £40k to £60k a year before tax. Adjust the ratios based on whether you’re 30 or 70—younger folks can lean more into stocks, older ones into bonds.
But wait, you say, “What about taxes?” Ah, the uninvited guest. Dividends in the UK have an allowance (£1,000 tax-free for basic rate, £500 for higher rate—thanks, Treasury). Use ISAs (tax-free wrapper) to shield up to £20k a year. With a million, it’ll take a few years to shift it all in, but start now.
And don’t forget fees. A 1% management fee on £1m is £10,000 a year—enough to buy a small car. Use low-cost trackers or a flat-fee broker. Your future self will send you a thank-you note.
The Final Truth
Uncle Geoff asked me, “Is it really that simple?” No, not quite. Markets wobble, inflation creeps, and you’ll have moments where you want to sell everything and buy gold bars shaped like llamas. But if you stick to the boring plan—diversify, reinvest, and ignore the news—that million pounds can drip-feed you an income for decades.
Remember: income investing is a marathon in slippers. You don’t need to be a genius; you just need to be patient and a bit lazy. So pour yourself a drink, set up those automatic payments, and let the money do the heavy lifting. Your lawnmower-obsessed uncle would approve.