
You’re in the middle of a perfectly fine Tuesday—maybe you’re eating leftover pizza and watching a cat video—when your phone buzzes with an unknown number. You answer with a casual “Hello?” and suddenly a stranger introduces themselves as a representative from “Debt Recovery Associates.” Your brain short-circuits. Wait, what? That’s right: a debt collection agency is calling. And you’re about to enter a bizarre, legally-enforced dance that’s equal parts anxiety, absurdity, and surprising facts.
The First 10 Seconds: Your Brain Melts
Your first instinct is pure fight-or-flight. You might freeze, stammer, or say something genius like “I’m not home right now.” Classic. But here’s the kicker: the person on the other end has done this a thousand times today. They’re not a villain in a trench coat—they’re probably a bored call center agent with a script and a mild disdain for their job.
And here’s a surprising fact: you have more power than you think. The Fair Debt Collection Practices Act (FDCPA) is your invisible shield. It’s like a superhero cape, but instead of flying, it makes collectors follow strict rules. For example, they can’t call you before 8 a.m. or after 9 p.m. Unless they want to get yelled at by a federal judge.
Must Read
The Script: A Masterclass in Dramatic Pauses
Debt collectors love to use scary words like “lawsuit,” “wage garnishment,” and “immediate action required.” They speak in a low, serious tone, like a movie trailer narrator. Don’t panic. That’s their script. Yours is simpler: you can ask for a validation letter—a written proof that the debt is yours. By law, they must send it within five days of first contacting you.
Fun fact: many debt collectors don’t actually own the debt. They bought it for pennies on the dollar from the original creditor, like a bargain bin at a thrift store. So that $500 credit card bill might have been bought for $20. Yes, your debt is a coupon deal for them.
The Best (And Funniest) Way to Respond
If you’re feeling brave, try this: say, “Please send me all communication in writing.” Suddenly, the collector’s tone changes. They hate paperwork. It’s like asking a vampire to cross a bridge of garlic. They’ll likely say, “Are you refusing to pay?” You say, “Nope, just want it in writing.” That’s your win.
 How Do Debt Collectors Collect Debt
But here’s where it gets weird: you can also ask them to stop calling entirely. Send a written request to cease communication. After that, they can only contact you to confirm they’ve stopped, or to notify you of a lawsuit. It’s like pressing a mute button on a bad karaoke singer.
The “Uh Oh” Moment: When They Threaten Legal Action
Some collectors will say, “We’re sending this to our legal department.” Cue dramatic music. But here’s a secret: most collectors bluff. The vast majority of debts are for small amounts—under $500—and suing you costs them more than the debt is worth. Think of it like suing someone over a missing pizza slice. Ridiculous, right?
Still, don’t ignore it if it’s real. If they do sue, you must respond. But for most calls, the worst that happens is they call again tomorrow. And the day after. And then they sell your debt to another agency, who calls you with a slightly different accent. It’s like a terrible game of telephone, but with threats.
Surprising Facts That Will Make You Laugh (And Cringe)
Fact one: Debt collectors can’t tell your boss, your mom, or your neighbor about your debt. Unless they want to be fined $10,000 per violation. So if they call your workplace and leave a message like, “Call us about your overdue TV subscription,” they’re breaking the law. You get to be the IRS of that phone call.
 How to Handle Debt Collection Calls | Midland Credit Management
Fact two: There’s a statute of limitations on most debts. In many states, after three to six years, they can’t sue you. But—here’s the trap—if you make a payment or even say, “I acknowledge this debt,” the clock resets. It’s like hitting “restart” in a video game you want to end.
Fact three: Some collectors use automated “predictive dialers” that call multiple numbers at once. If a human answers, they patch in a collector. That’s why you sometimes hear dead air for three seconds. They’re literally connecting you to a stranger in a cubicle.
The Grand Finale: How to End the Call
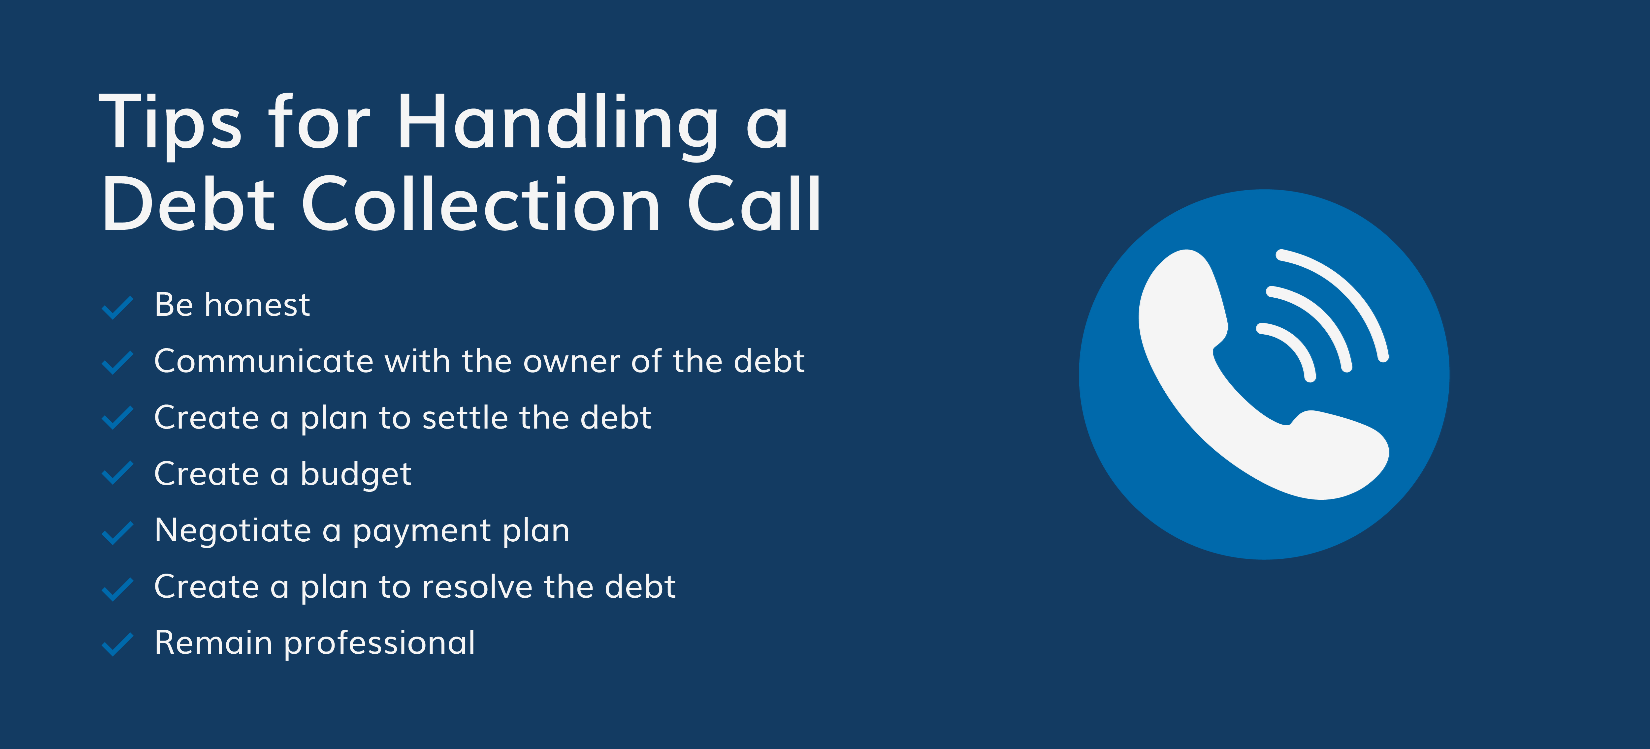
The best move? Stay calm, be clear, and stick to facts. Say: “I don’t have information about this debt. Send me a validation letter. Thank you, goodbye.” Click. Mic drop. Then block the number and go back to your pizza. You’re not ignoring the problem—you’re following the law’s playbook.
And if you ever feel overwhelmed, remember: millions of people get these calls. It’s a multibillion-dollar industry built on your anxiety. But you’re armed with the FDCPA, a pinch of humor, and the knowledge that most collectors are just trying to meet a quota. Now, go answer that call with the confidence of someone who knows the rules. And maybe don’t answer after 9 p.m.—you’ve got rights, and a date with your couch.